Access Home Equity for Future Liquidity
A high-net-worth client wanted a safety net. Instead of liquidating investments, we structured a HELOC against the equity position of his property.
Access Home Equity for Future Liquidity
The Challenge
A high-net-worth client with significant real estate holdings wanted a safety net — access to liquidity in case an unforeseen need came up down the road. The instinct for most people in this situation is to look at their investment accounts. But pulling money out of the market to create that cushion means selling assets, which often means triggering a taxable event and interrupting a strategy that's been working.
He didn't want to touch his investments. He wanted a way to have liquidity standing by, without cost or consequence, until, or unless, he actually needed it.
The Solution: A Home Equity Line of Credit
Instead of liquidating investments, we structured a HELOC against the equity position of his property.
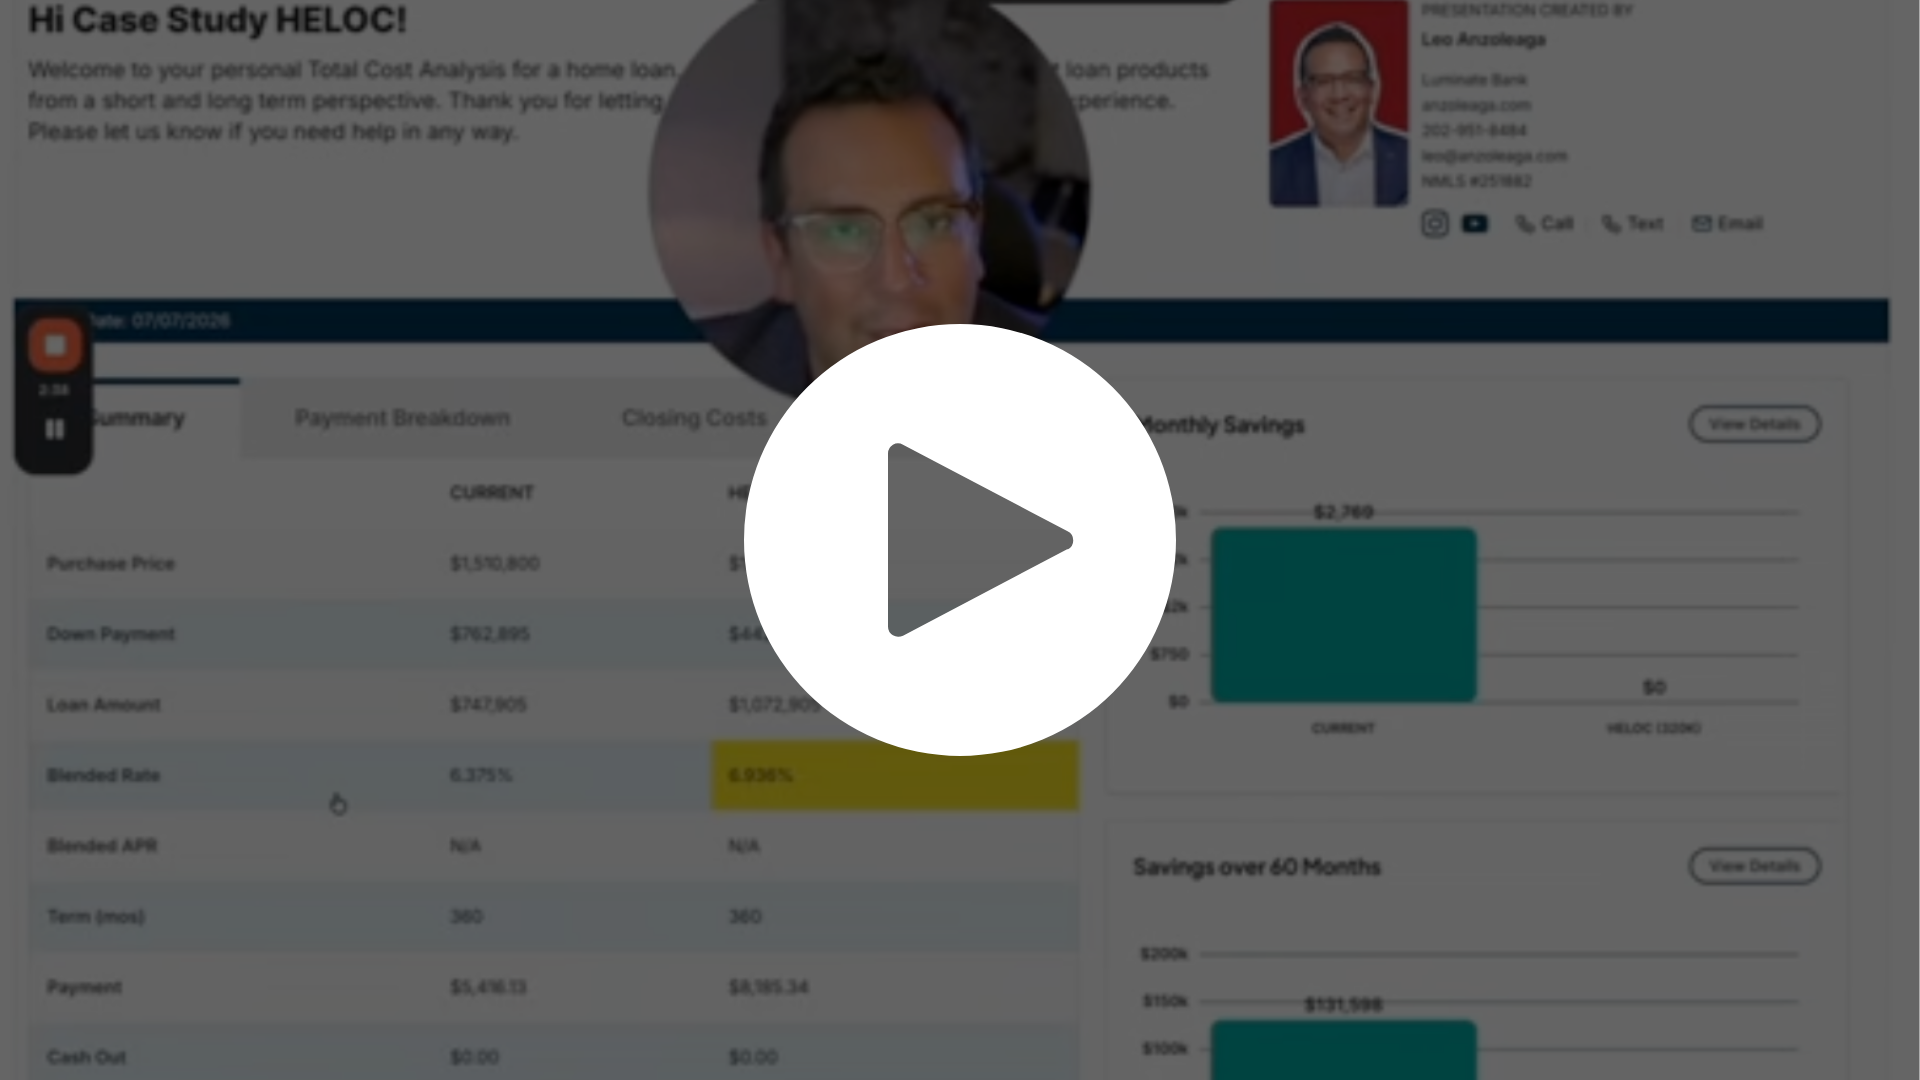
Watch the full case study here.
Here's how it works:
- Typically a 20-year amortization schedule with a 10-year open draw period
- Rate is tied to Prime, plus a multiplier based on loan-to-value, DTI, and credit profile
- Requires only a small initial draw at closing — in this case, $25,000 — with the rest of the line available and untouched
- The client can hold the line open for up to 10 years without using it further, or draw on it the moment a need arises
Why This Mattered
The client's real goal wasn't spending the money — it was having it available without disturbing his balance sheet. That meant:
- No need to liquidate investments and lose years of compounding growth
- No taxable event triggered by a market sale
- Immediate access to capital the moment a real need shows up, instead of scrambling to raise cash under pressure
The Trade-Off
A HELOC comes with its own rate, and when layered on top of an existing first mortgage, it's worth understanding the blended cost of both loans together — not just the HELOC rate in isolation. We walked through what the effective, blended rate looked like across both instruments so the client had a full picture before moving forward.
The Result
The client closed on the HELOC with a strong equity position behind it and an open line ready if he ever needs it. His investments stayed untouched and fully invested. He didn't have to choose between liquidity and long-term growth — he got both.
When to Consider a HELOC for Liquidity
- High-net-worth clients who want a liquidity cushion without disrupting their investment strategy
- Anyone whose advisor is recommending they avoid a taxable liquidation event
- Clients with strong equity positions who want optionality, not necessarily immediate cash
- Situations where "just in case" access matters more than a lump sum today
What makes this work: we help advisors and their clients look past the headline rate and understand the real, blended cost of leveraging equity — so the decision is made with full financial context, not just one number.
If you have a client who could benefit from this kind of liquidity strategy, I'd love to help. Email me at Leo@Anzoleaga.com to learn more.
Increase your Mortgage Under Management
Join our program and begin enhancing the way you advise clients on their mortgages and more today.